Business Visualizations
Study Shows Where the Oldest and Youngest Business Owners Live

There are many kinds of entrepreneurs in the U.S., from family-owned restaurants to tech startups. The team at Ooma studied data on the ages of business owners in every state, then mapped out the results to identify any regional patterns. As we can see from the map, business ownership aspirations aren’t limited to a certain age. The team used data from the U.S. Census Bureau to create their map and examined major metropolitan areas to determine where the oldest and youngest business owners reside.
Click below to zoom.
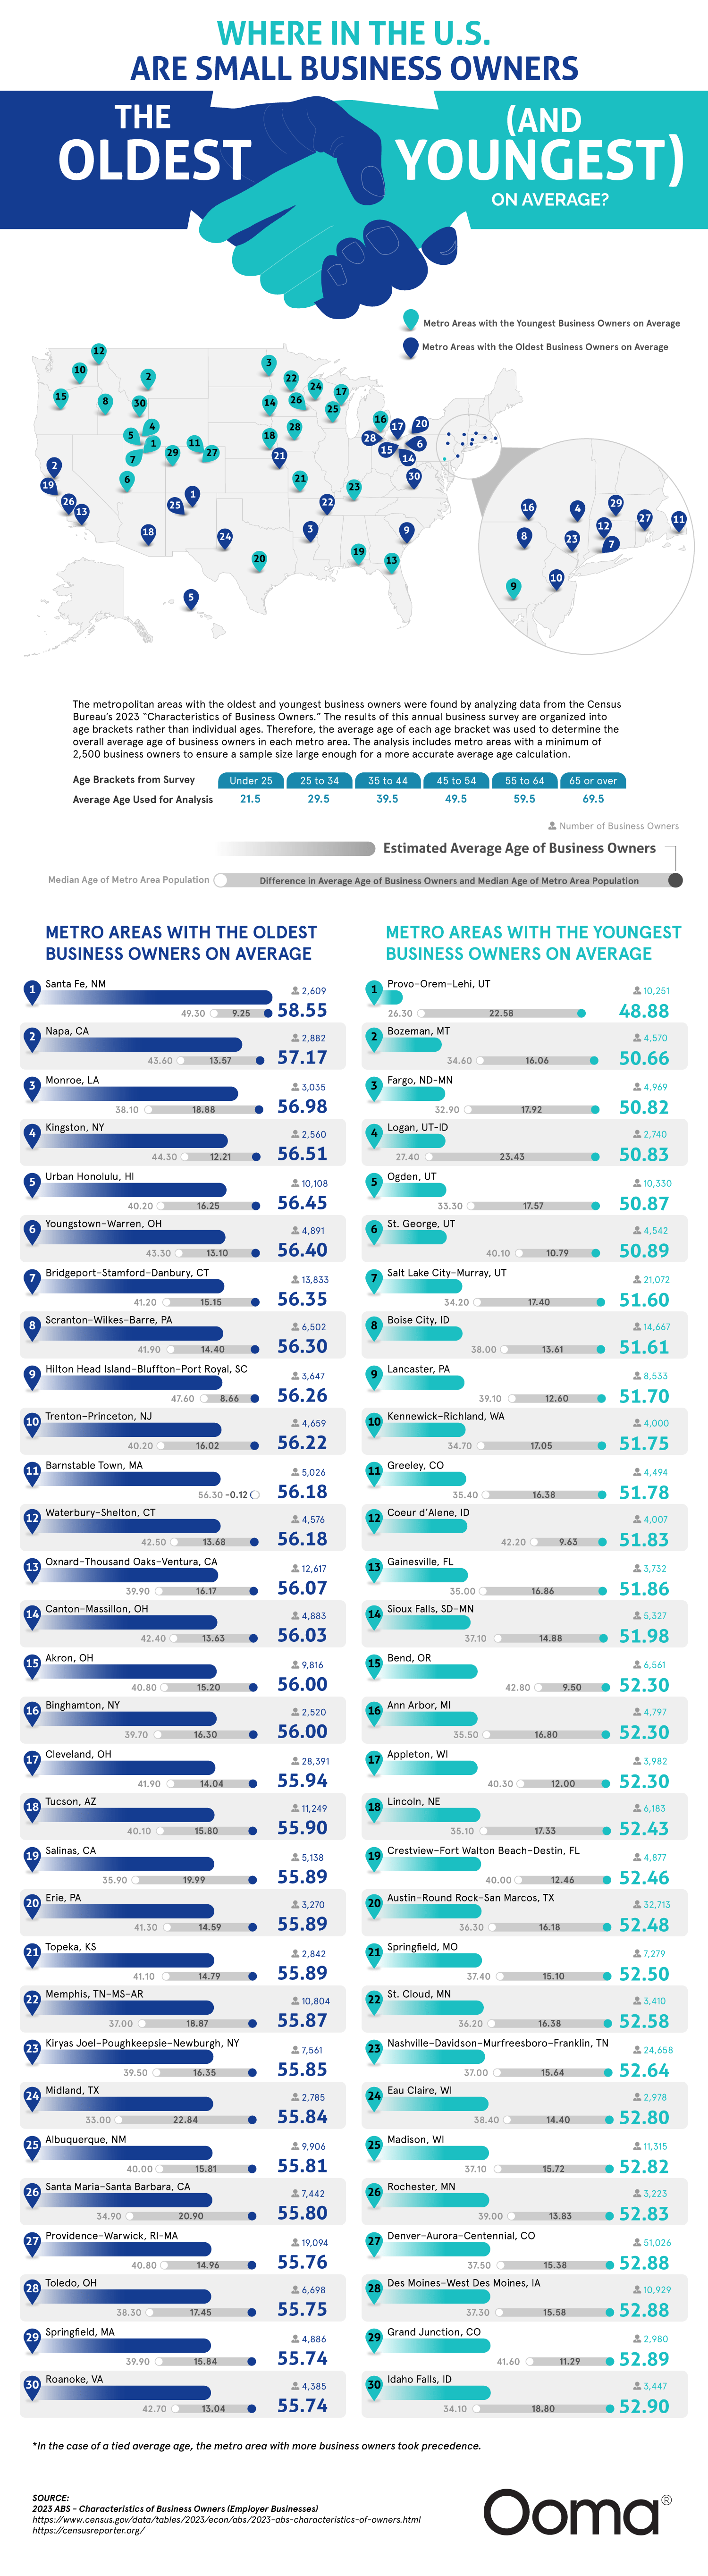
The youngest business owners live in Provo-Orem-Lehi, Utah, where the average age of a business owner is a bit below 49. This is lower than the national average by about a decade. Overall, many young entrepreneurs live in Utah. This could be due to the low cost of living and a family-focused culture with plenty of support for younger business owners. Utah’s economic boom surely helps these businesses get off the ground.
These ten cities have the youngest business owners in the country:
- Provo-Orem-Lehi, Utah
- Bozeman, Montana
- Fargo, North Dakota-Minnesota
- Logan, Utah-Idaho
- Ogden, Utah
- George, Utah
- Salt Lake City-Murray, Utah
- Boise City-Idaho
- Lancaster, Pennsylvania
- Kennewick-Richland, Washington
Utah certainly claimed many spots on this list, but we also see that the Rockies and Upper Midwest support a lot of young business owners. University towns and low living costs all help support younger people in gathering the resources to start their own business.
Moving on to the cities with the oldest business owners, we find that Santa Fe, New Mexico, has the oldest business owners, with an average age of around 59 years. Many of the cities topping this list are located in retirement-friendly areas with slower population growth and higher cost of living. This suggests these are more difficult locations to start a small business in, requiring owners to have more resources and experience to get started.
These ten cities have the oldest business owners:
- Santa Fe, New Mexico
- Napa, California
- Monroe, Louisiana
- Kingston, New York
- Urban Honolulu, Hawaii
- Youngstown-Warren, Ohio
- Bridgeport-Stamford-Danbury, Connecticut
- Scranton-Wilkes-Barre, Pennsylvania
- Hilton Head Island-Bluffton-Port Royal, South Carolina
- Trenton-Princeton, New Jersey
According to the national data the team collected, most business owners are in their late 40s to early 50s. This might surprise some people, as the media often reports on bright young entrepreneurs founding exciting tech startups. However, consider that there are many different types of small businesses in America. In most cases, starting a successful business requires resources, time, and connections that can only be acquired through age and experience. In general, the spread of ages isn’t very large, so it seems the team has pinpointed the ideal age to start up a business.
This map can provide valuable insights into the American economy, both by region and as a whole. While the team identified some regional patterns in entrepreneurship, it appears that entrepreneurs across the nation share many commonalities.

Moving into a first apartment is a rite of passage, but the math behind making it a reality is becoming a bigger obstacle. The metros with the strongest job markets also have the steepest living costs, and over the past few years, rent in these areas has climbed faster than paychecks. Cheap rent isn’t the only solution, though. Thin wages and flat hiring shut young people out of many cities.
Rove Lab’s new analysis identifies the cities in the middle ground with the most to offer young people establishing their lives. The study examined the 100 most populous U.S. metro areas and scored each one on 10 different metrics grouped into three weighted categories.
Click below to zoom.
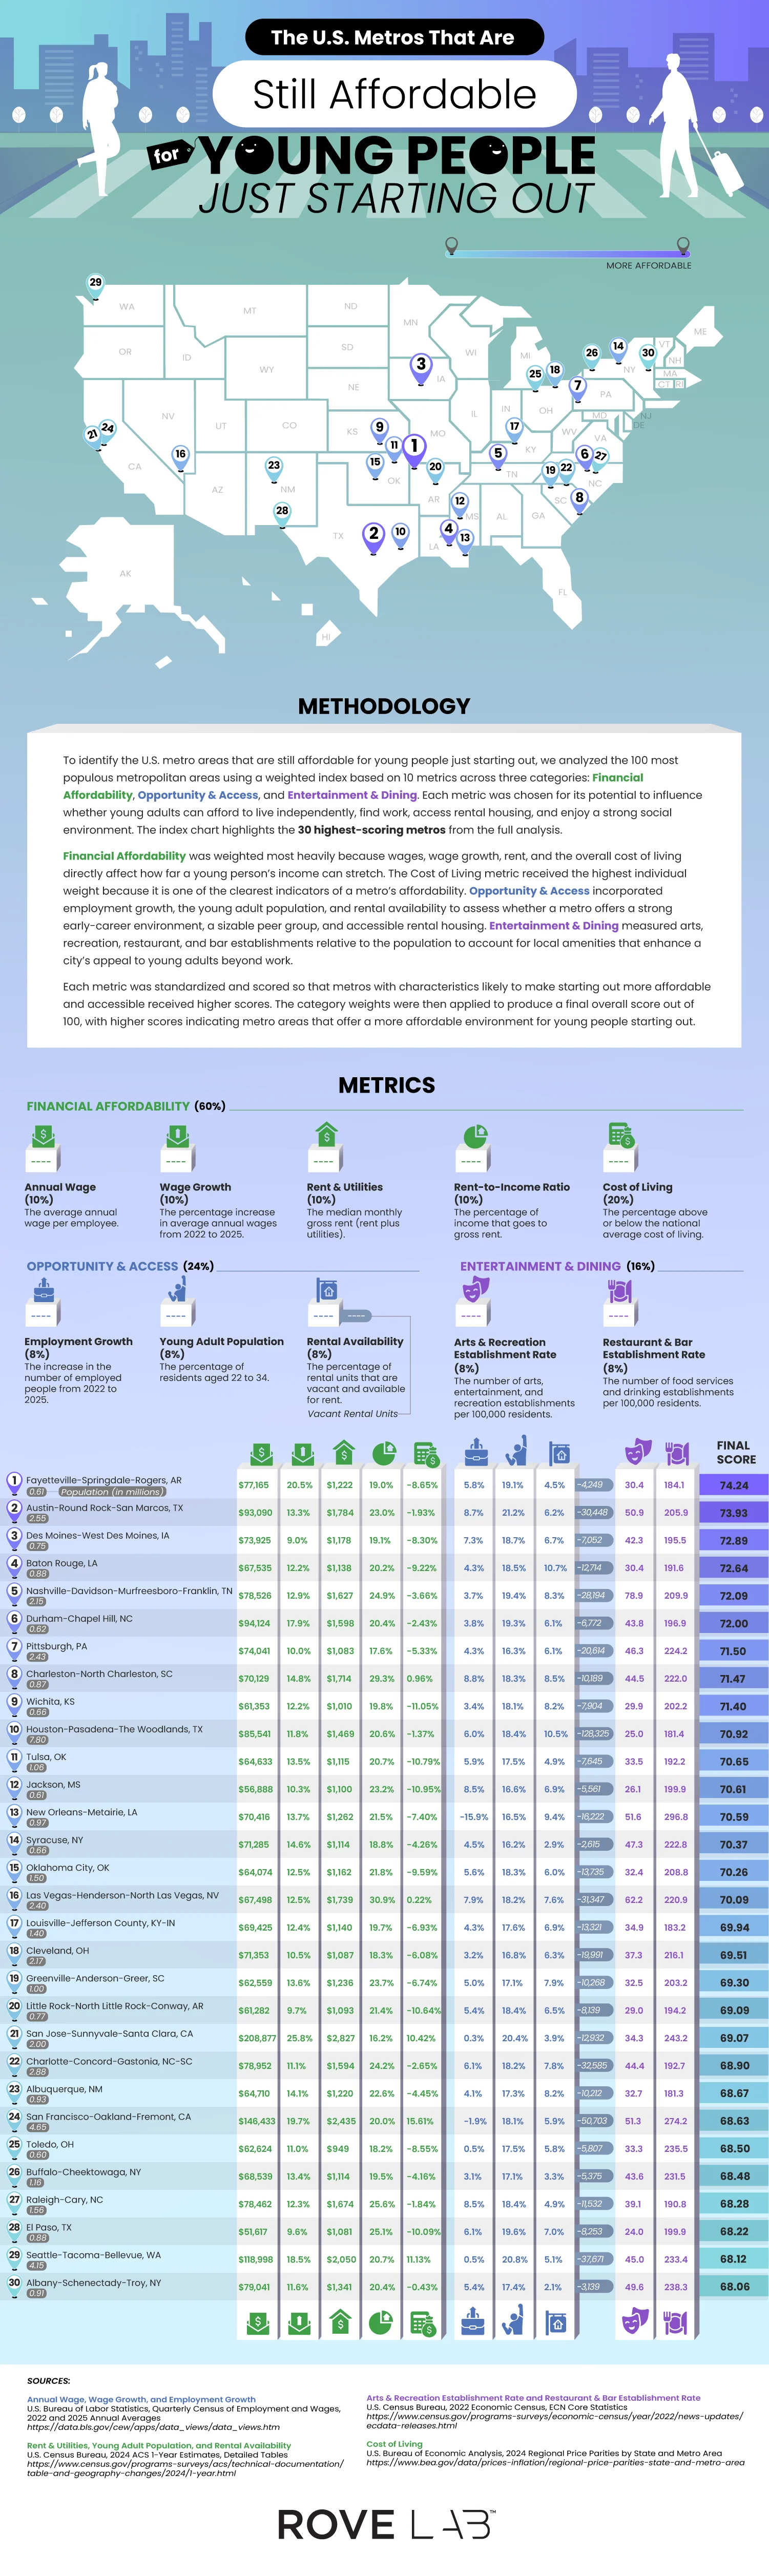
Financial affordability was the most important category, carrying 60% of the weight. This category covers average annual wage, wage growth, median rent and utility costs, rent-to-income ratio, and cost of living relative to the national average. Cost of living alone received 20% of the weight, the heaviest single metric in the study. Opportunity and access accounted for 24% and included employment growth, number of residents between 22 and 34, and amount of rental vacancy. The final 16% went to entertainment and dining, tracking the number of arts and recreation venues and restaurants and bars per 100,000 residents. Each metric was standardized, scored, and weighted into a final number out of 100.
The winning city was Fayetteville-Springdale-Rogers, Arkansas, with a score of 74.24. This isn’t an obvious winner until you look at the numbers. Wages increased by 20.5% from 2022 to 2025, with the average wage at $77,165 and a cost of living that’s 8.65% below the national average. This combination creates a rent-to-income ratio of 19%, leaving young people with money to save, potentially for the elusive dream of homeownership. Fortune 500 companies, Walmart, J.B. Hunt, and Tyson, have a home in the area and likely explain wage strength.
Austin-Round Rock-San Marcos followed with a 73.93 score, driven by a thriving tech sector that’s seen 8.7% employment growth, and the area offers 30,000 vacant rental units for newcomers. Des Moines, Baton Rouge, and Nashville round out the top five.
A few cities earned high rankings thanks to low housing costs. Pittsburgh was seventh overall with a rent-to-income ratio of 17.6%. Wichita, ranked ninth, has low rent and utilities and a low cost of living that’s 11.05% below average. Toledo, number 25 on the list, has the cheapest housing of all cities on the list, with an average of $949 a month.
The most surprising cities on the list are Californian. San Jose-Sunnyvale-Santa Clara ranks 21st, and San Francisco-Oakland-Fremont lands 24th, despite costs of living well above the national average. Salaries do the heavy lifting, averaging $208,877 and $146,433, respectively. This pulls down San Jose’s rent-to-income ratio to 16.2%, the lowest on the list.
If you were to ask the average American on the street to name the industries that power the national economy, they’ll likely reply “manufacturing” or “tech.” But the Bureau of Economic Analysis says otherwise. As Ooma’s study shows, real estate, rental, and leasing hold the biggest slice of the U.S. economy.
In 2024, the U.S. produced more than $29 trillion in economic output, which outstripped Germany, China, and Japan combined. Looking at how gross domestic product (GDP) breaks down by industry shows the value added by sector after subtracting the costs of the inputs that industry consumed. For example, a carmaker buys steel, rubber, and semiconductors. The value added is the difference between those purchases and the selling price of the finished car. Add up that gap, the value added across every industry in the country, and you arrive at the GDP.
Click below to zoom.
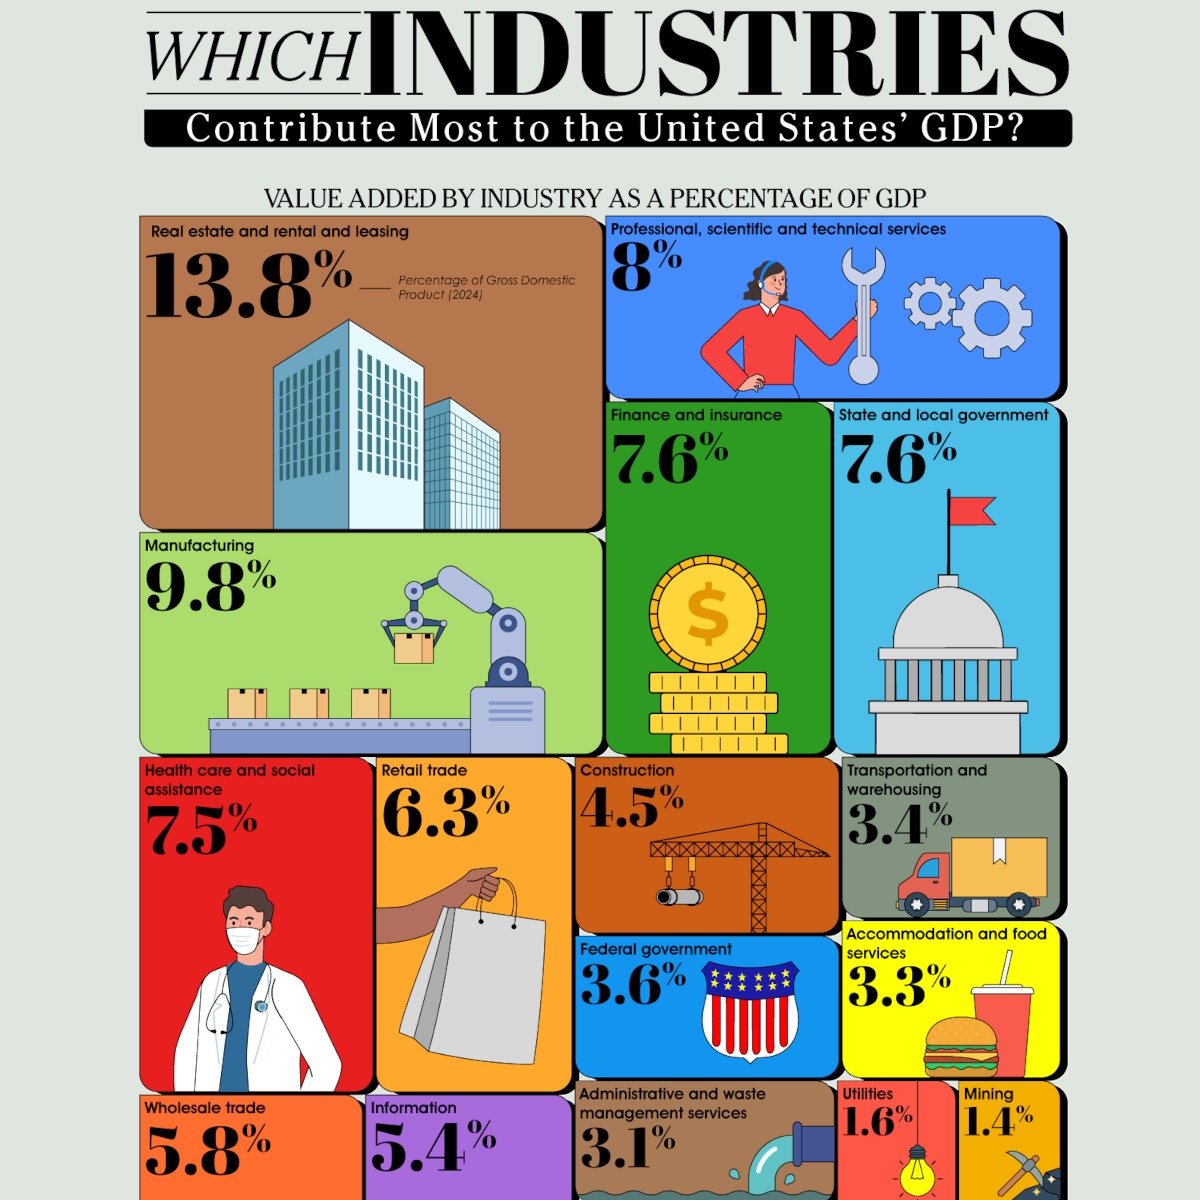
When Ooma ranked industries by their GDP, they found out that the money is concentrated in these industries:
Real estate, rental, and leasing – 13.8%: Real estate alone accounted for $3.68 trillion, the biggest of any sub-industry in the economy. Every mortgage payment, property tax bill, apartment lease, and commercial rent check pours into this sector. Rising home ownership costs over the past decade have pushed more citizens into renting, which has only inflated this industry.
Manufacturing – 9.8%: Factory employment has fallen for forty years due to automation and offshoring, but output hasn’t fallen. Chemical products created $554 billion, and computer and electronic products contributed $299.8 billion to the U.S. economy, helping keep the nation among the world’s top manufacturing nations despite a smaller workforce.
Professional, scientific, and technical services – 8.0%: This industry is made up of law firms, consultancies, engineering firms, and software developers. Legal services alone created $387.7 billion, and computer systems design added $552.2 billion to the American economy. This strongly shows how the American economy leans toward knowledge work.
Finance and insurance – 7.6%: Credit intermediation and Federal Reserve banks generated $1.01 trillion, insurance carriers contributed $791.8 billion, and securities and commodity contracts brought in $396.1 billion.
State and local government – 7.6%: Many rankings leave out these sectors, but government at the state and local level added $2.07 trillion, second only to real estate among all the sub-industries.
Health care and social assistance – 7.5%: Ambulatory care brought in $1.08 trillion and hospitals contributed $691.5 billion. This reflects genuine demand from an aging population and the fact that the U.S. spends more per capita on healthcare than any other developed nation.
Below these top-tier industries, retail trade, wholesale trade, information (Google, Meta, cloud providers, telecom), data processing, and internet publishing followed. Construction closed out the top ten industries at 4.5%, rising and falling in contributions with the real estate sector.
The largest components of American GDP aren’t the ones that produce a physical product. They’re the industries that manage property, deliver care, sell expertise, and move money.
Student Choice has published the 2026 updated version of its study, ranking the most popular college degrees by return on investment after five years in the workforce. The team’s premise is timely as they examine a hot topic: the cost of higher education. The average cost of college now exceeds $43,000 per year, so entering the workforce with these student loans became a high-stakes game. The analysis pairs the top 25 majors in 2026, based on a previous Student Choice study, with earnings data from the U.S. Bureau of Labor Statistics to calculate how much a graduate earns in their first five years relative to their four-year tuition investment. They illustrated their findings by ranking 20 degree types compared to 40 common occupations.
Click below to zoom.
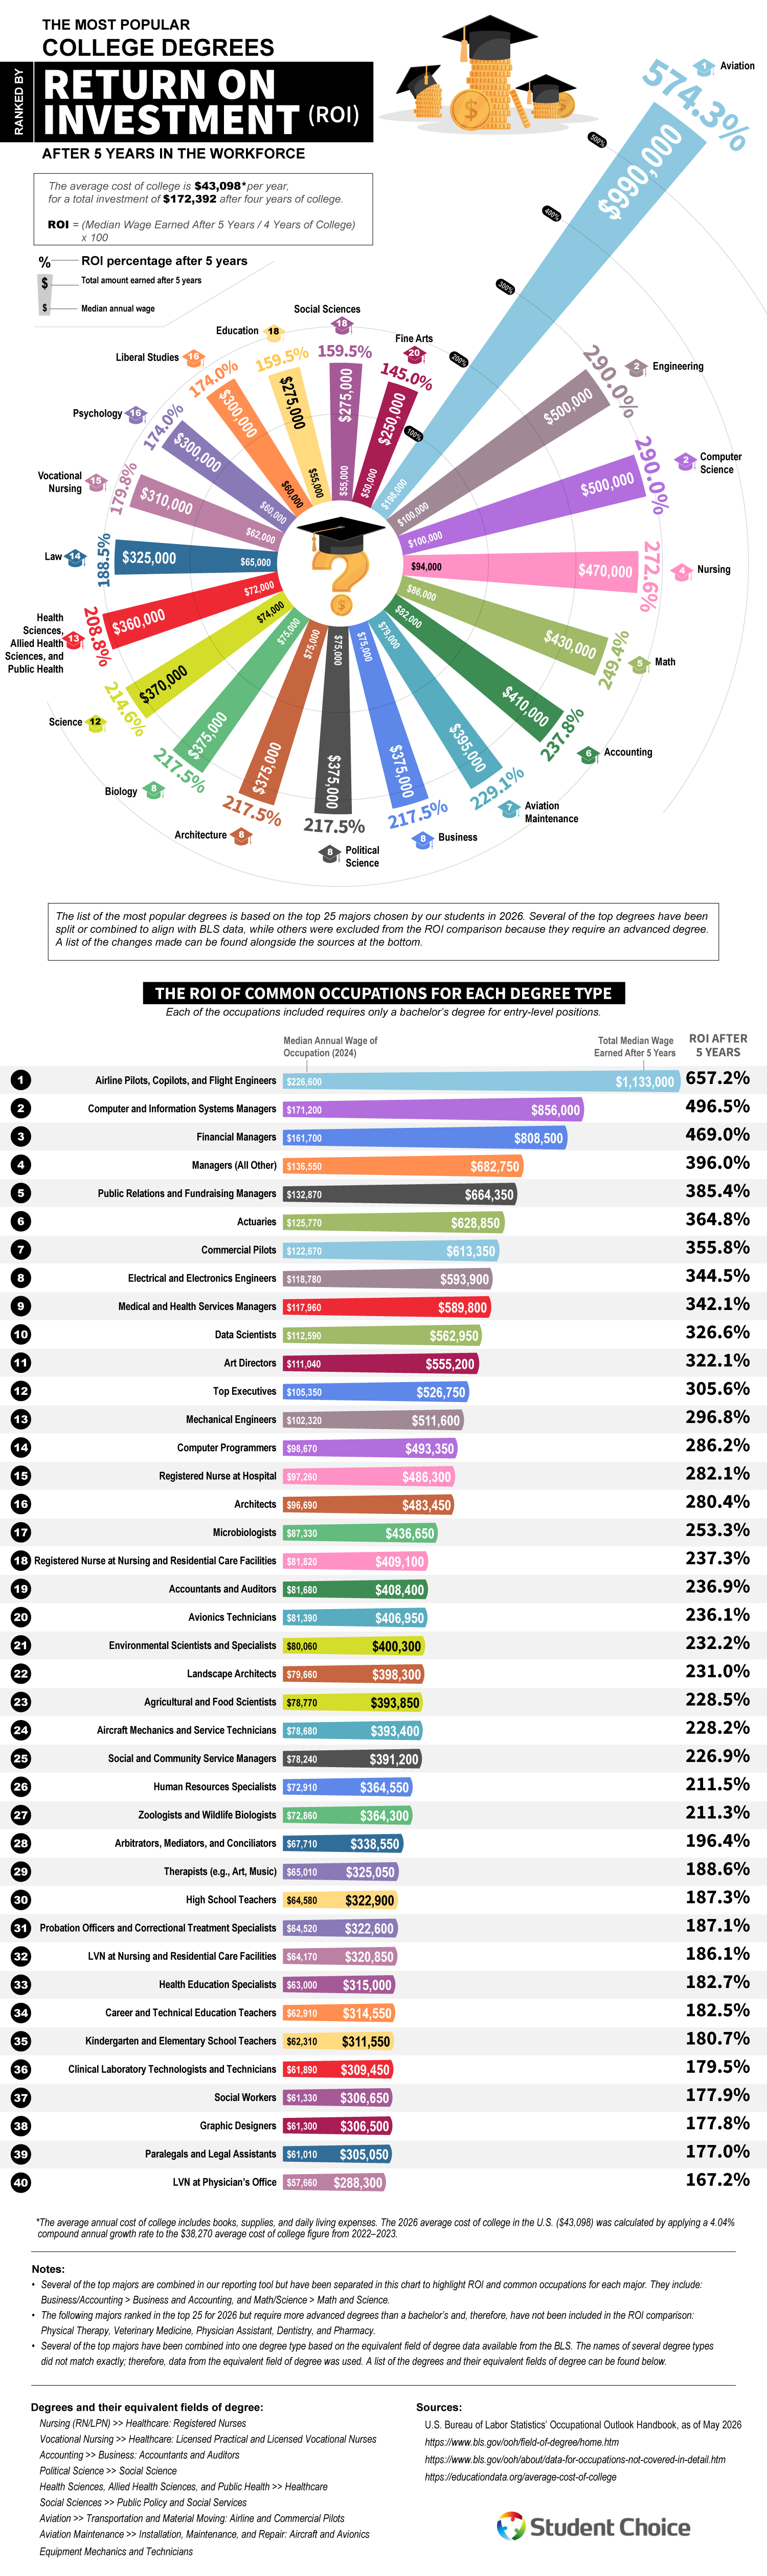
The team used a simple methodology. The average cost of college is $43,098 per year for a total investment of $172,392 for four years, with ROI calculated as median wages earned over five years divided by the four-year college cost. Majors that require advanced degrees like physical therapy, veterinary medicine, physician assistant, dentistry, and pharmacy were excluded from the ROI comparison even though these majors rank in the top 25.
Aviation tops the rankings chart, claiming the leading spot by a wide margin because of its astounding 574.3% ROI after five years, boosted by the median annual wage of $198,000. The field’s popularity is likely due to high pay and a looming pilot shortage as veteran airline workers retire. Engineering and computer science tied for second place at 290% each with median wages of $100,000 a year.
Healthcare and quantitative fields round out the upper tier. Nursing ranks fourth with an ROI of 272.6%, followed by math at 249.4% and accounting at 237.8%. Business, political science, architecture, and biology all tie for eighth at 217.5%, based on a $75,000 median wage. Education and social sciences sit near the bottom of the list at 159.5%, and fine arts at the bottom at 145%.
The study’s most helpful section might be the table that shows how career choice within a major can dramatically outperform the degree’s baseline. Aviation graduates who became airline pilots, copilots, or flight engineers reached a 652.7% return on a median wage of $226,600. Computer and information systems managers hit 496.5%, financial managers reached 469%, and public relations and fundraising managers reached 385.4%. Even lower-ranked majors can have exceptions. For example, fine arts majors who become art directors have a 322.1% return with a median salary of $111,040. Math majors working as actuaries earn 364.8%.
Overall, though, this study shows us that getting a degree pays off. Even accounting for student debt, the data suggests that degrees can double or triple the initial investment within five years. While most people will work for about four decades after student life, the returns will continue to compound. There is a growing preference for specialized, career-focused degrees with clear pathways into established professions so students can enjoy the ROIs we see here.
-
 Business Visualizations2 years ago
Everything Owned by Apple
-
 Business Visualizations2 years ago
America’s Most Valuable Companies Ranked by Profit per Employee
-
 Business Visualizations2 years ago
The Biggest Fortune 500 Company in Every State
-
 Business Visualizations1 year ago
The Biggest Employers by Industry
-
 Charts2 years ago
Map Uncovers Countries with Most Powerful Passports
-
 Business Visualizations12 months ago
The Largest Companies in America That Are Still Run by the Person Who Founded Them
-
 Timelines2 years ago
Timeline Charts the Development of Communications Technology
-
 Timelines2 years ago
The Evolution of Baby Names: A Century of Trends